Source: Sifted | Fonte: Sifted
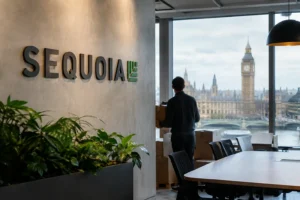
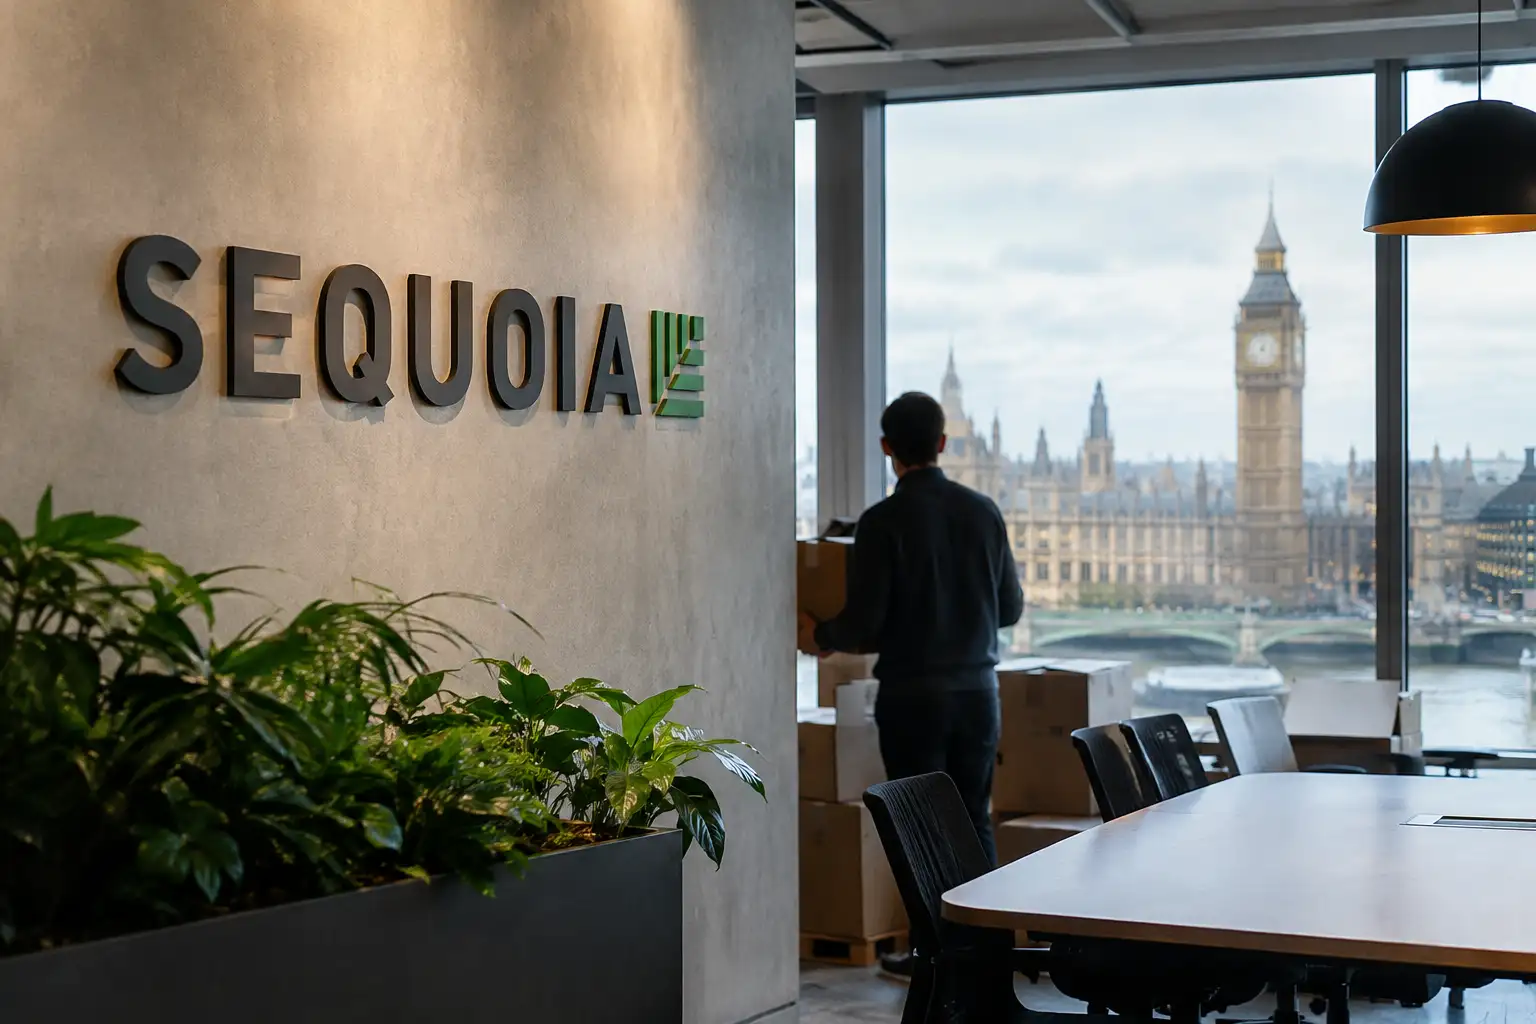
Sequoia Capital, one of the world’s most important venture capital firms, has decided to close its London office, a move that has prompted significant debate across the European startup ecosystem. The decision marks a notable strategic retreat for a firm that had positioned its UK presence as a bridgehead into the broader European market, and it raises pointed questions about how American mega-funds assess the long-term opportunity on this side of the Atlantic.
The closure does not mean Sequoia is abandoning European investments entirely. The firm has indicated it will continue to back European founders, likely managing those relationships from its US and Israeli offices. However, the symbolic weight of withdrawing a physical presence from London, one of Europe’s dominant financial and technology hubs, should not be underestimated. For founders and co-investors, proximity and local knowledge have always mattered in early-stage dealmaking.
The timing is notable. European venture markets have faced a prolonged correction since the peak of 2021, with deal volumes and valuations contracting sharply across most geographies and sectors. Exit routes remain constrained, with the IPO window largely shut for growth-stage companies and strategic M&A activity subdued relative to historical norms. In this environment, large funds with global mandates are understandably rationalising where they deploy operational resources.
Yet the move could also create meaningful opportunity for European-native investors. Firms such as Atomico, Index Ventures, and a growing cohort of sector-specialist funds have consistently argued that European founders are better served by investors with deep local networks and an understanding of the regulatory, cultural, and commercial landscape that defines doing business across the continent. A reduced footprint from Sequoia may reinforce that thesis and channel more founder attention toward homegrown capital.
For the broader European ecosystem, the episode underscores a structural tension that has persisted for years: the continent produces world-class technical talent and an increasing number of breakout companies, yet it continues to depend heavily on US venture capital for large-ticket growth rounds. Building sufficient late-stage and growth equity capacity domestically remains one of the defining challenges for European institutional investors, policymakers, and fund managers in the decade ahead.
***
Sequoia Capital, una delle società di venture capital più influenti al mondo, ha deciso di chiudere il proprio ufficio di Londra, una mossa che ha innescato un dibattito significativo nell’ecosistema startup europeo. La decisione rappresenta un notevole ritiro strategico per una società che aveva posizionato la propria presenza nel Regno Unito come testa di ponte verso il mercato europeo più ampio, sollevando interrogativi precisi su come i mega-fund americani valutino l’opportunità di lungo periodo in questa parte dell’Atlantico.
La chiusura non significa che Sequoia abbandoni del tutto gli investimenti europei. La società ha indicato che continuerà a sostenere i fondatori europei, gestendo probabilmente queste relazioni dai propri uffici statunitensi e israeliani. Tuttavia, il peso simbolico del ritiro della presenza fisica da Londra, uno dei principali hub finanziari e tecnologici d’Europa, non dovrebbe essere sottovalutato. Per i fondatori e i co-investitori, la prossimità e la conoscenza locale hanno sempre avuto un ruolo determinante nelle operazioni di dealmaking nelle fasi iniziali.
La tempistica è significativa. I mercati del venture capital europeo hanno attraversato una prolungata correzione dal picco del 2021, con volumi di operazioni e valutazioni in netto calo nella maggior parte delle geografie e dei settori. I canali di uscita restano limitati, con la finestra per le IPO sostanzialmente chiusa per le società in fase di crescita e l’attività di M&A strategico ridotta rispetto alle norme storiche. In questo contesto, i fondi di grandi dimensioni con mandati globali stanno comprensibilmente razionalizzando l’allocazione delle risorse operative.
Tuttavia, la mossa potrebbe creare opportunità concrete per gli investitori di matrice europea. Società come Atomico, Index Ventures e una crescente schiera di fondi specializzati per settore hanno costantemente sostenuto che i fondatori europei siano meglio serviti da investitori con reti locali profonde e una comprensione del panorama regolatorio, culturale e commerciale che caratterizza il fare impresa nel continente. Una presenza ridotta di Sequoia potrebbe rafforzare questa tesi e orientare maggiore attenzione dei fondatori verso il capitale autoctono.
Per l’ecosistema europeo nel suo complesso, l’episodio evidenzia una tensione strutturale che persiste da anni: il continente produce talenti tecnici di livello mondiale e un numero crescente di aziende di rilievo, eppure continua a dipendere fortemente dal venture capital statunitense per i round di crescita di maggiore entità. Costruire una capacità sufficiente di growth equity nelle fasi avanzate a livello domestico rimane una delle sfide determinanti per gli investitori istituzionali europei, i responsabili politici e i gestori di fondi nel prossimo decennio.